
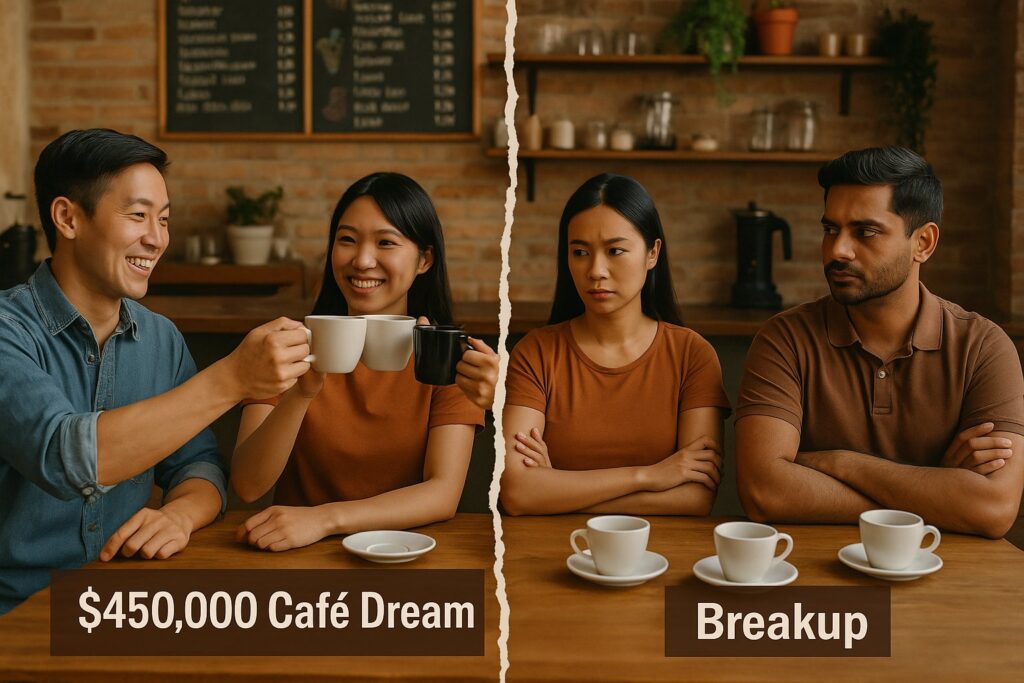
It started like many Singapore SME stories do. Three good friends — Jason, Mei Ling, and Raj — bonded over late-night kopi sessions and decided to turn their dream into reality: a café of their own.
Each put in $150,000. No banks, no loans — just trust, laughter, and a shared vision. With $450,000, they rented a shophouse near Bugis and rolled up their sleeves.
Raj poured his energy into the kitchen, crafting a playful brunch menu — eggs benedict with prata, cold brew kopi, even a nasi lemak waffle. Mei Ling took charge of the café’s look and feel, designing the space and building a loyal following on Instagram. Jason handled the numbers: suppliers, rent, and the daily balancing of books.
A viral TikTok sent queues snaking down the block. Weekends were packed. Business was finally picking up.
The Cracks Begin to Show
But success brought new pressures.
Raj was burning out and wanted to hire more kitchen staff.
Mei Ling argued customers complained about cramped seating and pushed for renovations.
Jason urged caution: “Let’s not spend too quickly. We still owe suppliers and the landlord wants next quarter’s rent upfront.”
That’s when Mei Ling made a proposal.
Her friend Sharon had been following the café’s rise and wanted to invest. “She’s willing to put in $100,000,” Mei Ling said. “That gives us funds for renovations and staff.”
Jason and Raj, tired of constant debates about money, agreed without much thought. More cash sounded like the quick fix they needed.
At first, Sharon was just an investor. But slowly, her influence grew. She questioned Jason’s accounting, suggested cheaper suppliers, and pushed Mei Ling to “take the café brand national.”
“Why is Raj insisting on artisanal eggs when regular ones will do?”
“We need more influencers. Don’t waste money on chairs — spend it on marketing.”
Before long, Sharon wasn’t just offering opinions — she was shaping decisions. With her and Mei Ling aligned, Jason often found himself outvoted. Raj, caught in the middle, grew increasingly frustrated.
Politics had entered the café.
The Pressure From Outside
The café was no longer just between three friends. Families and Sharon’s voice were now in the mix.
-
Raj’s uncle kept asking when dividends would come.
-
Mei Ling’s parents reminded her their retirement savings were tied up.
-
Sharon pushed relentlessly for expansion: “If you don’t grab this wave, someone else will.”
-
Jason’s wife warned him: “You’re losing more than money here — you’re losing yourself.”
The café that once united friends now carried the weight of competing agendas.
The Messiness of Exit
The breaking point came when the mall offer for a second outlet resurfaced. Sharon championed it aggressively. “This is your chance to scale. Don’t be small-minded.”
Jason refused. “We don’t even have six months of cash buffer. Expanding now is suicide.”
Lines were drawn. Mei Ling and Sharon stood together. Raj wavered but leaned toward growth out of exhaustion. Jason was isolated.
Talks turned to exit. Jason suggested selling his stake. But here’s the problem — they had never once discussed exit terms when they set up the café. No agreements, no formula, no plan.
That meant everyone had their own idea of what the shares were worth.
-
Sharon claimed Jason’s stake was worth less because he was the “blocker” to growth.
-
Mei Ling insisted any buyout should factor in Sharon’s new capital.
-
Raj, caught in the middle, felt torn between loyalty to Jason and promises of relief if they expanded.
With no agreed rules, valuation became guesswork. Meetings turned into shouting matches. Lawyers were consulted. Friendships fractured.
They went in as three friends with $450,000 and a dream. They came out divided, resentful, and poorer — financially and emotionally.
The café didn’t survive. Neither did the friendships.
The Hidden Cost of Equity
On paper, equity from friends and family looks like “easy money.” There are no monthly repayments, and investors genuinely want to see you succeed.
But equity comes with strings: ownership means influence. Bring in more investors, and politics will follow. If things turn sour, you’re not just losing business partners; you may lose relationships too.
What About Debt?
Debt feels scarier upfront. Bank officers ask tough questions. Monthly repayments loom large.
But here’s the upside: the lender doesn’t tell you how to run your café. As long as you service the loan, your decisions remain yours. It’s a clean relationship — money in, interest out, no arguments over direction.
The Takeaway
There’s no right or wrong answer. Equity works if expectations are crystal-clear and roles are defined from day one. Debt works if you’ve got the cash flow discipline to service it.
But here’s the question every SME owner should ask before raising money:
Am I willing to share control of my business, or do I want to keep decisions in my own hands?
Because sometimes, the cost of “easy money” is far higher than interest rates.
📌 3 Questions Before You Take Money From Friends or Family
-
Control — Are you prepared to share decision-making with them?
-
Exit — What happens if one party wants out? Do you have agreed terms on how shares will be valued and bought back?
-
Boundaries — How will you separate business discussions from personal relationships?
If you don’t have clear answers to these, debt might be the cleaner choice.
💡 Pro Tip:
“Friends-and-family” money doesn’t always need to be equity. You can also structure it as debt — a loan with agreed repayment terms. You can further structure it such that it can converted to equity at a later date with certain milestones being achieved.
That way, your loved ones still support you financially, but the rules of engagement are clear: they’re lenders, not co-owners. It avoids messy control struggles and simplifies exits later on.