
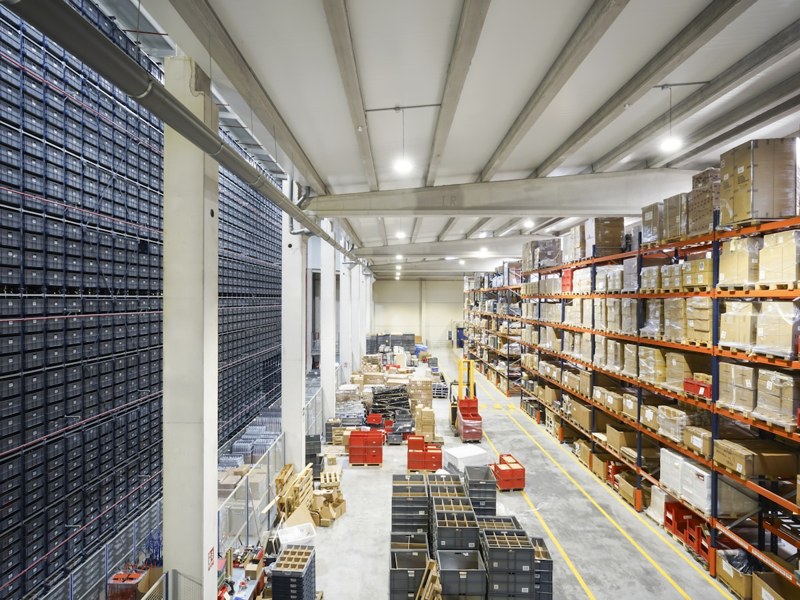
If stock is growing while cash falls, compare existing inventory with purchase commitments before placing another order. Recorded sales growth may conceal cash tied up in unsold items or deposits.
Raffles Corporate Services works with a panel of experienced Singapore law firms who offer cost-effective and efficient legal service and advice. This article is general information only and is not legal advice.
Work from stock by product and location, not one overall inventory value.
Verify the physical and accounting position
Reconcile counts, goods in transit, returns and stock held by third parties. Identify damaged, obsolete or disputed goods separately.
A warehouse report and ledger balance can differ for understandable reasons, but the differences need evidence. Review reliable record keeping with the accountant, consistent with ACRA’s director obligations.
Example: a reorder arrives before old stock sells
A supplier shipment is committed based on an earlier sales forecast. Demand has slowed, and the company is already holding several months of the same product. Assess the remaining commitment and cash dates before assuming a new promotion will solve the problem.
Build the stock-to-cash schedule
- Quantity, cost and age by material product.
- Realistic expected sales and receipts.
- Open orders and cancellation terms.
- Deposits, freight and final supplier payments.
- Storage and other holding costs.
- Downside assumptions and decision dates.
Separate a forecast selling price from an accounting valuation conclusion. Ask the accountant to assess any write-down under the applicable reporting framework.
Review options under the actual contracts
Discuss revised quantities, delivery timing or other arrangements with appropriate authority. Do not assume a purchase order can be cancelled without consequence.
Discounting stock also needs a margin and cash review. More orders are not automatically helpful if fulfilment requires further spending before customers pay.
Control the next replenishment decision
Set review thresholds using actual demand, lead times and funding capacity. Keep significant assumptions visible and update them with real sales.
Record decisions and responsibilities so finance and purchasing operate from the same plan. Escalate an inability to meet obligations for specialist advice.
Does high stock value mean good liquidity?
No. Assess when stock can realistically turn into available cash.
Related practical business guides
Read our company deadline planning guide, accurate decision records checklist and funding delay guide.
Get help with the next step
Email [email protected] or WhatsApp +65 8501 7133. Our accounting team and tax advisers can assist with financial and tax questions. Legal advisers from our associated law firms can assist with contracts, employment matters, business disputes and financial-distress questions.